U.S. Existing-Home Sales Hit a 16-Year Low: High Mortgage Rates and Affordability Challenges Keep Buyers Away
The U.S. housing market is showing signs of growing pressure as fewer Americans purchase existing homes. Even though more properties are becoming available for sale, high borrowing costs and expensive home prices continue to make buying difficult for many households.
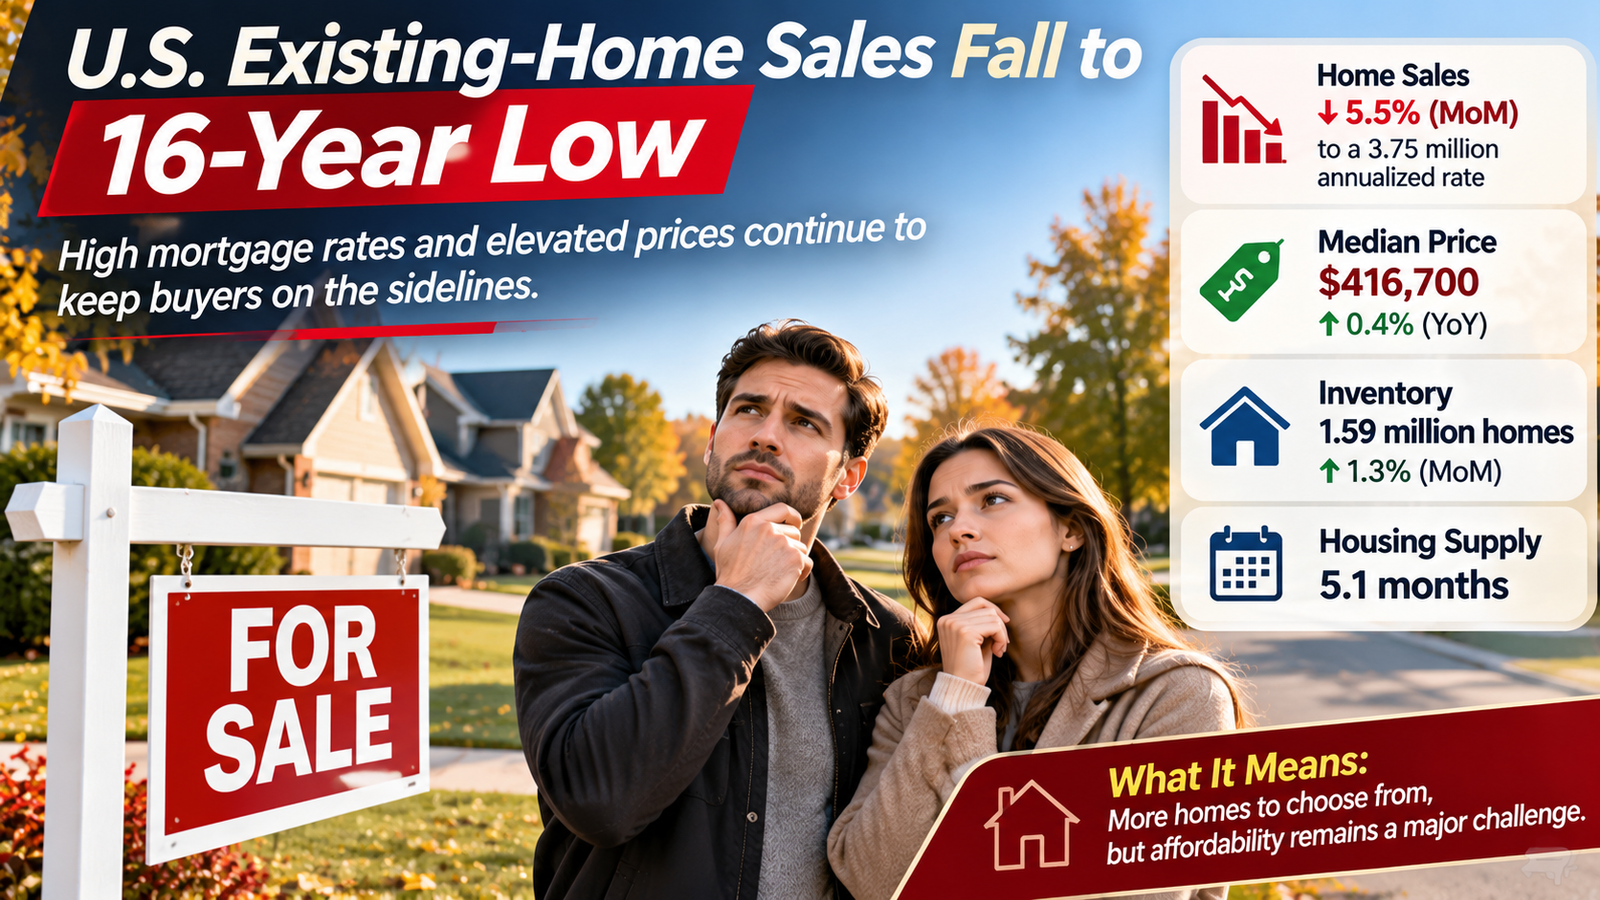
According to the National Association of REALTORS® (NAR), existing-home sales declined by 5.5% in October 2026, reaching a seasonally adjusted annual rate of 3.75 million. Compared with October 2025, sales were down 8.8%. This represents the slowest sales pace since August 2010.
The latest figures highlight an unusual situation in the American housing market: buyers have more homes to consider, but many still cannot comfortably afford to purchase them.
October Housing Market: The Key Numbers
Here are the major findings from NAR's October report:
- Existing-home sales: Down 5.5% month over month to an annualized rate of 3.75 million.
- Annual sales comparison: Down 8.8% from October 2025.
- Median existing-home price: $416,700, up 0.4% year over year.
- Available inventory: 1.59 million homes, up 1.3% from September.
- Housing supply: 5.1 months, compared with 4.7 months in September.
- First-time buyers: Accounted for 29% of purchases, down from 32% a year earlier.
- Median time on market: 35 days, compared with 33 days in September.
These figures show that the slowdown is not simply about a shortage of homes. Financing costs and affordability are also playing a major role.
Why Are Americans Buying Fewer Homes?
Mortgage rates remain one of the biggest obstacles for prospective buyers.
Freddie Mac data cited in NAR's report shows that the average 30-year fixed mortgage rate was 7.33% in October 2026. That was higher than September's 6.86% and October 2025's 6.25%.
Even a relatively small increase in mortgage rates can make a substantial difference to a household's monthly budget. Buyers who could previously afford a particular property may now need to consider a smaller home, make a larger down payment or postpone their purchase.
Home prices are adding to the pressure. The national median price for all existing-home types reached $416,700, representing a 0.4% increase from the previous year. This was the 40th consecutive month of annual price increases.
Although price growth has slowed, homeownership remains expensive when mortgage payments, insurance, property taxes and maintenance are included.
Housing Inventory Is Improving, but Affordability Remains a Problem
There is some encouraging news for buyers.
The number of existing homes available for sale increased to 1.59 million in October. That was 4.6% higher than a year earlier.
The supply of available homes also increased to 5.1 months, its highest level since November 2015, according to NAR.
A larger selection of homes can give buyers more time to compare properties and negotiate with sellers. It may also reduce the urgency that characterized markets with very limited inventory.
However, increased supply does not automatically make housing affordable. A home can remain financially out of reach even when its seller is willing to negotiate.
Realtor.com also reported that approximately 20.5% of active listings had price reductions in October. This suggests that some sellers are adjusting their expectations to attract buyers.
For prospective homeowners, this could mean more opportunities to negotiate, particularly in markets where listings are taking longer to sell.
Housing Affordability Has Become a Major Concern
One of the most important findings in the October report is the decline in housing affordability.
NAR's Housing Affordability Index stood at 100.7 in October, compared with 107.3 in October 2025. The index declined across all four major U.S. regions.
The regional annual declines were:
- Northeast: 8.7%
- Midwest: 7.2%
- South: 5.4%
- West: 5.2%
This helps explain why more housing inventory has not translated into stronger sales. Buyers are still facing financial pressure, even when additional properties become available.
First-time buyers are particularly affected. They generally have less accumulated home equity and may find it difficult to save for a down payment while managing everyday expenses.
Their share of existing-home purchases fell to 29% in October, compared with 32% a year earlier. Historically, first-time buyers have accounted for around 40% of home purchases.
This declining participation is an important sign of the challenges facing people trying to enter the housing market.
Regional Housing Markets: The West Experiences the Sharpest Decline
The national slowdown is not affecting every part of the country equally.
NAR's October figures show that sales declined month over month in three regions, while the Northeast remained unchanged.
Northeast: Existing-home sales remained unchanged at an annualized rate of 470,000. The median price was $519,600, up 3.2% from October 2025.
Midwest: Sales declined 3.2% to an annualized rate of 900,000. The median price reached $324,300, an annual increase of 1.5%.
South: Sales fell 6.5% to an annualized rate of 1.73 million. The median price was $360,900, down 0.4% year over year.
West: Sales recorded the largest monthly decline, falling 9.7% to an annualized rate of 650,000. The median price was $624,300, unchanged from a year earlier.
The West's 14.5% annual decline in sales was also the steepest among the four regions.
These differences matter because national housing statistics do not tell the complete story. A buyer looking in the Midwest may encounter very different prices and negotiating conditions from someone purchasing in California or another Western market.
What Does the Slowdown Mean for Sellers?
Sellers may need to reconsider their pricing strategies.
With more homes available and properties taking longer to sell, buyers have additional opportunities to compare listings. An overpriced property may struggle to attract serious offers, particularly when competing homes have reduced their asking prices.
However, the market is not showing signs of widespread financial distress among homeowners. NAR reported that distressed sales, including foreclosures and short sales, accounted for only 2% of transactions in October.
That suggests many existing homeowners are not being forced to sell because of financial difficulties.
For sellers, realistic pricing, good property presentation and flexibility during negotiations may become increasingly important.
What Should Real Estate Investors Watch?
For investors, falling home sales do not automatically mean that the U.S. property market has become unattractive.
A slower market can create opportunities to negotiate with sellers who need more time or are willing to accept a lower offer. Rising inventory may also give investors a wider selection of properties.
However, investors should not make decisions based only on national sales figures.
Rental demand, local employment, property taxes, insurance costs, maintenance expenses and expected resale values all need to be considered.
NAR also reported that individual investors and second-home buyers accounted for 20% of existing-home transactions in October, up from 16% a year earlier. This indicates that investor and second-home activity remains an important part of the market, even as overall sales decline.
Cash purchases accounted for 29% of transactions, up from 27% in September.
These figures suggest that buyers with available capital may have a different experience from households that depend heavily on mortgage financing.
What Could Happen to the U.S. Housing Market Next?
The direction of the housing market will depend on several factors, particularly mortgage rates, employment conditions, household income and the availability of homes at affordable prices.
If mortgage rates decline, some buyers who have delayed their purchases may return to the market. NAR Chief Economist Lawrence Yun has also pointed to the possibility of pent-up demand if borrowing costs ease.
However, lower mortgage rates alone may not solve every affordability problem. Home prices, property taxes, insurance and household income will continue to influence purchasing decisions.
For now, buyers appear to have more choices and somewhat greater negotiating power, while sellers must compete more actively for attention.
Ask a question
Have a question about this article? Ask below and our team will reply.